Family offices
Direct ownership rather than fund exposure, a longer hold, and a low tolerance for surprises after close.
Family offices · Private equity · Independent sponsors
I find cash-flowing businesses that never reach a banker's list, and I tell you where the deal breaks before you are in it. You buy better, or you walk away early and keep your money.
Video placeholder
Two minutes on what I look for, what I pay for it, and the point at which I walk away.
Which side of the table
“The banker, the broker, the seller’s advisor. Everyone in the room is paid to make the deal look good. I will tell you where it breaks and you can WIN!”
What I buy
Most buy boxes are written to sound open, which leaves you guessing and costs you a call to find out. This one is written so you can rule a target in or out before you pick up the phone. Here is what I take, and what I pass on.
Established, profitable, and running on something more than the founder's own hours.
You are buying a business, not a job. The cash flow you underwrite should still be there the week after the owner stops answering the phone.
Below the threshold where a banked process makes sense, and above the size where there is nothing to buy.
It is the band where you are up against a handful of buyers rather than a field of them, and where the seller is usually talking to you rather than to a process.
Fixing a broken business is a different risk, a different timeline, and a different practice.
If you want a turnaround, buy one on purpose, with the team and the hold period it needs. You will not be handed one here by accident.
No pre-revenue, no concept stage, and nothing whose only growth path runs through the current owner.
Owner dependency is what quietly breaks a deal in the year after close. It gets found before you are looking at the target, not after you own it.
Who I work with
Different mandates, different hold periods, different reasons for being at the table. The same need: a straight read on a deal before you are committed to it.
Direct ownership rather than fund exposure, a longer hold, and a low tolerance for surprises after close.
A thesis already written, and a need to know quickly whether a target sits inside it or outside it.
A first or second acquisition, buying an operating business rather than adding another line to a portfolio.
Three ways in
Deal flow
For intermediaries, brokers and buyers holding something that does not fit their own box. What I want to see, how fast I come back, and what confidentiality looks like before anything changes hands.
How it worksBuyer cohort
Application-only. Bring a target you are actually looking at, build the buy box, put a Capital Access Model valuation on it, and get to a letter of intent. Not a course. A deal you are already working.
Apply to the next cohortCapital
Capital comes from FM, which lends against deals it underwrites itself. I work alongside buyers on structure when the deal warrants it, described as it is, with the fee disclosed before anyone starts.
How capital works hereMeet Fadi
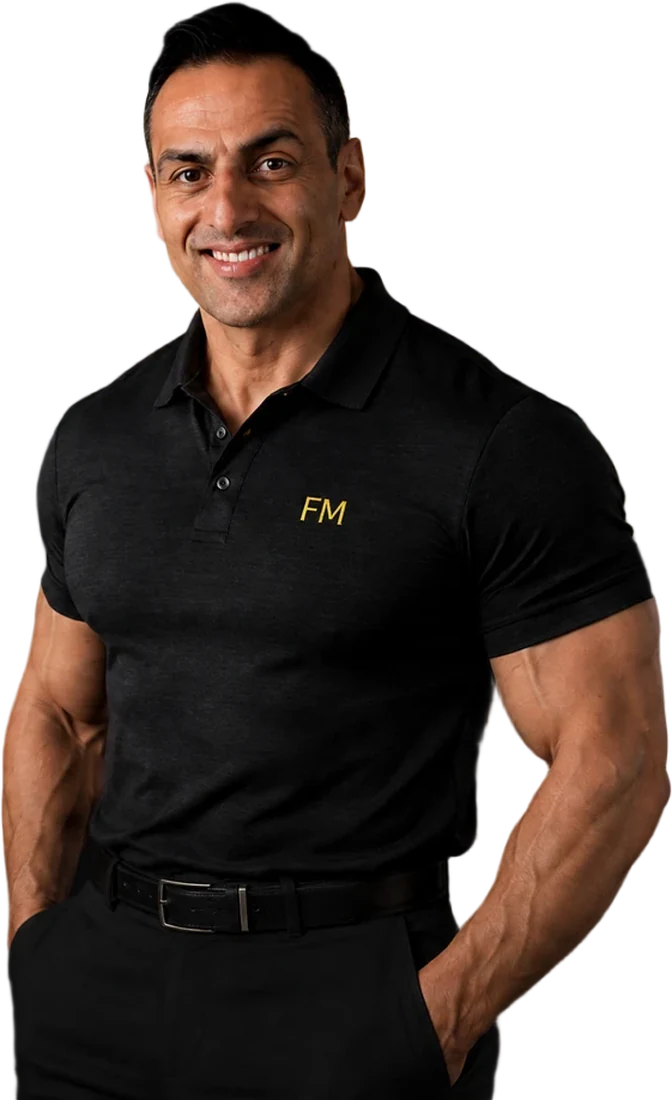
Fadi came to the United States from Jordan. He spent ten years competing professionally as a natural bodybuilder, where preparation was visible and the result had to hold up next to people who had done the work too.
Today he brings that same standard to acquisitions, business advisory and capital. Get close to the real business. Look at what is there. Say what is missing. Then do the work that makes the next move possible.
He likes working with drivers: athletes, operators, investors and owners who want the truth about a deal while there is still time to use it.
“The work shows. The numbers show. Talk is not enough.”
Partnered with and featured on
Next step
Send what you are looking at. If it fits the box you get a real read on it. If it does not, you get told that, quickly.